Understanding Loan-to-Value on a Patek Loan
A collateral loan against a Patek Philippe rests on one figure that decides how much cash the object can release: the loan-to-value ratio. Understanding how that number is reached turns a headline offer into something you can actually judge.
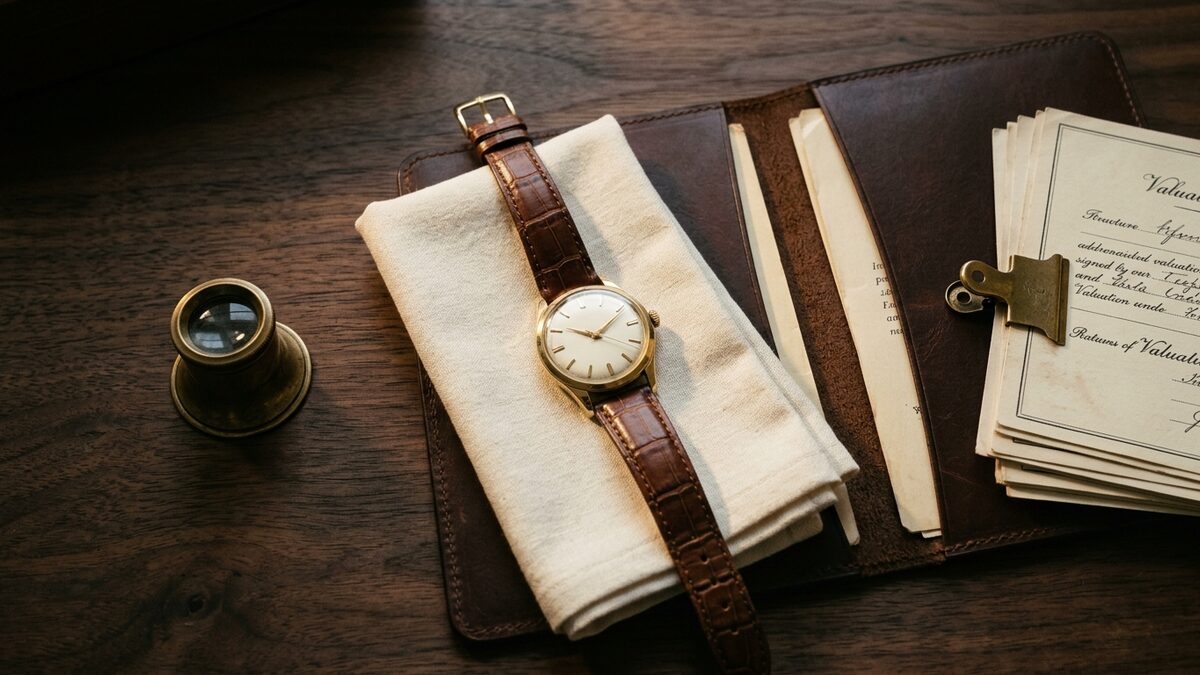
What the loan-to-value ratio on a Patek loan actually measures
Every collateral loan begins with a valuation, but the sum an owner is offered is rarely the full number a specialist assigns to the object. The gap between the two is the loan-to-value ratio, usually written as a percentage. If a Patek Philippe is assessed at a working value and the advance is seventy percent of it, the loan-to-value ratio is seventy percent. The remaining margin is not a fee; it is the lender's cushion against price movement, selling costs, and the time it would take to convert the watch into cash if a loan were never repaid.
That distinction matters, because it explains why two honest parties can look at the same watch and arrive at different numbers. The valuation answers a simple question: what is this object worth? The loan-to-value ratio answers a harder one: how much of that worth can be advanced safely? A high ratio is not automatically generous, and a conservative one is not automatically mean. Each reflects how confident the lender is that the assessed value would survive a quick, forced sale.
For Patek Philippe specifically, that confidence tends to run higher than for most names, because the secondary market for the maison's work is deep and consistent. A well-known reference in sound condition has buyers waiting in almost any market. That liquidity is the quiet reason loan-to-value ratios on these objects often sit above what a comparable-value watch from a thinner market would command.
What pushes the figure up or down
Four things do most of the work in setting the ratio. The first is the reference itself. A perpetual calendar, a steel sports model with a strong following, and a classic Calatrava each behave differently on the resale market, and the lender prices that behaviour in. References with steady, liquid demand support a higher advance; a complication that appeals to a narrower audience may be assessed more cautiously, however desirable it is.
Condition is the second lever. Original dials, unpolished cases, and crisp hallmarks all support a stronger figure, because they protect the resale value the loan is written against. Service history helps for the same reason. Signs of a refinished dial, heavy polishing, or replaced parts do not disqualify a watch, but they narrow the pool of buyers who would pay top of range, and the ratio softens accordingly.
Completeness of the set is the third factor, and it is easy to underestimate. The original box, the certificate of origin or an extract from the archives, and any additional links or accessories are part of what makes a Patek Philippe straightforward to resell. A full set with matching paperwork moves faster and closer to its ceiling, so it supports a firmer advance. A watch alone, with no papers, is still valuable, but it carries more friction, and the loan-to-value ratio reflects that friction.
The fourth factor is market liquidity at the moment of the offer. Even the right reference in the right condition is read against current demand. When a segment is trading briskly, a lender can be more comfortable advancing a larger share of value; when a segment has cooled, the same object may support a slightly lower ratio, not because the watch changed but because the speed of a sale did.
This is where an owner should shift attention from the headline number to the range beneath it. A loan-to-value ratio only means something once you know the value it is a percentage of. Before weighing any offer, it helps to establish the object's realistic private-sale range: not the highest asking price seen online, and not a quick-buy figure, but the band where comparable examples, in comparable condition and completeness, actually change hands. Recent results, honestly matched to your own watch, give you that band.
Read the advance against the lower end of that band rather than the top of it. If an offer represents a comfortable share of what the watch would fetch in a real, unhurried private sale, the ratio is doing its job. If it leans on the most optimistic figure you have seen, the percentage may look attractive while the underlying value is inflated, which serves no one. A sober valuation with a slightly lower headline ratio is often the stronger position, because it leaves room to repay and reclaim the object without strain.
Approached this way, the loan-to-value ratio stops being a figure to accept or reject and becomes a conversation you can join. You are not negotiating a percentage in the abstract; you are agreeing on what the object is worth today and how much of that worth can sensibly travel with the loan. An owner who understands both halves of that equation reads every offer with clear eyes.